Key Points
-
The Bureau of Labor Statistics will publish the September inflation report on Oct. 14, providing the final puzzle piece needed to calculate Social Security’s 2027 cost-of-living adjustment (COLA).
-
Two of President Trump’s policies are directly affecting consumer prices and boosting projections for next year’s Social Security raise.
-
Unfortunately, Trump bump-led raises come at a potentially steep cost to the program.
- The $23,760 Social Security bonus most retirees completely overlook ›
For Social Security’s more than 71 million traditional beneficiaries (retired workers, workers with disabilities, and survivors of deceased workers), the wait is almost over. In less than three weeks, on Oct. 14, the U.S. Bureau of Labor Statistics will publish the September inflation report and provide the final puzzle piece needed to calculate Social Security’s 2027 cost-of-living adjustment (COLA).
Social Security’s COLA represents the near-annual “raise” passed on to beneficiaries to offset the inflation they’ve faced. For instance, if the cost to purchase a broad basket of goods and services climbs by 3% from one year to the next, Social Security payouts would have to rise by the same percentage to avoid a loss of buying power.
Missed AI’s “Act 1”? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »
Next year’s COLA is shaping up as a history-maker, courtesy of President Donald Trump. It’ll mark the second straight year that beneficiaries will see their payouts boosted by a “Trump bump” and feature something no one’s witnessed since the 1990s. However, bigger Social Security checks come at a potentially steep cost to America’s leading retirement program.
The impact of President Trump’s policies on consumer prices is a good-news/bad-news scenario for Social Security. Image source: Official White House Photo by Daniel Torok.
Social Security’s 2027 Trump-led raise should be unique
Since the Consumer Price Index for Urban Wage Earners and Clerical Workers became Social Security’s inflation-measuring yardstick in 1975, inflation has been a common occurrence. Businesses should possess modest pricing power over their goods and services when the U.S. economy is growing.
But in 2026, we’ve witnessed two of President Trump’s policies provide an added boost to the prevailing inflation rate: tariffs and the Iran war.
In April 2025, President Trump unveiled his “Liberation Day” tariffs, consisting of a sweeping global tariff and dozens of higher reciprocal tariffs on dozens of countries. Even though the U.S. Supreme Court struck down these tariffs in February 2026, their impact on consumer prices last year provided a boost to Social Security’s 2026 COLA.
In July 2026, the Trump administration reinstated sweeping global tariffs, ranging from 10% to 12.5%, on more than 80 countries using a different justification. Assigning duties to imported goods can increase domestic production costs and lift consumer prices. In other words, tariffs should boost Social Security benefits yet again in 2027.
BREAKING: August CPI inflation comes in at 3.4%, in-line with expectations of 3.4%
Core CPI inflation falls to 2.4%, also in-line with expectations of 2.4%.
Month-over-month CPI inflation rose +0.4%, the biggest increase since May 2026.
Treasury yields are rising on the news.
— The Kobeissi Letter (@KobeissiLetter) September 11, 2026
Meanwhile, the effects of the Iran war on consumer prices can be directly seen at the fuel pump. Iran’s closure of the Strait of Hormuz over the last seven months has sent crude oil prices and fuel prices soaring.
According to the latest estimates from independent Social Security and Medicare policy analyst, Mary Johnson, and The Senior Citizens League (TSCL), a nonpartisan senior advocacy group, Social Security’s 2027 COLA is expected to be 3.5%.
If estimates from TSCL and Johnson prove accurate, it’ll mark the sixth consecutive year that Social Security’s cost-of-living adjustment has been at least 2.5%, with raises of 5.9% (2022), 8.7% (2023), 3.2% (2024), 2.5% (2025), and 2.8% (2026) preceding it. The last time Social Security recipients enjoyed six consecutive years with payout increases of at least 2.5% was in the 1990s, when COLAs clocked in between 2.6% and 5.4% from 1988 through 1997.
Thanks to two of President Trump’s policies, history should be made when Social Security’s 2027 raise is announced on Oct. 14.

Image source: Getty Images.
Social Security’s Trump bump-led raise comes at a steep cost to the program
While Social Security beneficiaries are likely to enjoy a sixth consecutive year with an above-average payout increase, beefier benefit checks come at a potentially steep cost to America’s leading retirement program.
Entering this year, Social Security’s financial outlook wasn’t on the best footing. While its long-term (75-year) funding shortfall has been growing for decades — the program’s unfunded obligation stands at an estimated $29.3 trillion through the year 2100 — it’s the projected depletion of the Old-Age and Survivors Insurance trust fund’s (OASI) asset reserves that has current and future beneficiaries concerned.
According to the 2026 Social Security Board of Trustees Report, the OASI’s asset reserves — the excess cash built up since inception that’s invested in special-issue, interest-bearing government bonds, as required by law — are forecast to run dry by the fourth quarter of 2032.
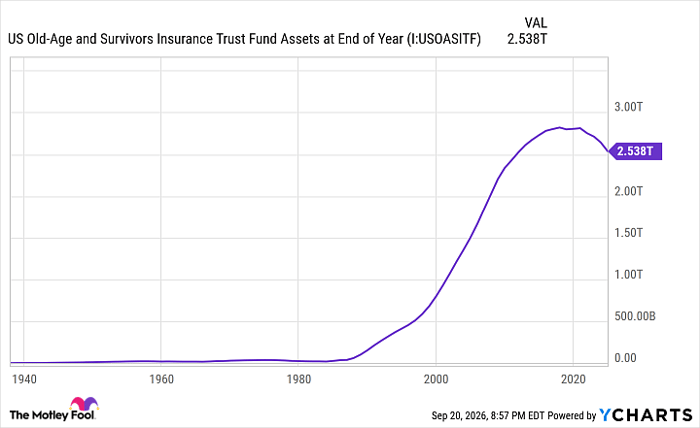
US Old-Age and Survivors Insurance Trust Fund Assets at End of Year data by YCharts
While there’s absolutely no risk of Social Security going bankrupt or halting benefits, the exhaustion of the OASI’s asset reserves in six years is projected to lead to sweeping benefit cuts of 22% for retired workers and survivors of deceased workers.
Here’s where things get dicey.
When the Social Security Board of Trustees calculates the short- and long-term solvency of the program’s trust funds, including the OASI, it takes into account a laundry list of variables, such as longevity, net migration into the U.S., and even average annual COLAs. In their modeling, the Trustees assume annual cost-of-living adjustments will be modest.
If TSCL’s and Johnson’s projections of a 3.5% Social Security raise in 2027 are accurate, the sixth-largest percentage increase to benefits since 1993 could drain the OASI’s asset reserves even faster than forecast. If the OASI’s excess capital is depleted more quickly than expected, the timeline to sweeping benefit cuts could be pushed from the fourth quarter of 2032 to an earlier date.
Bigger Social Security checks are fun… until you recognize the longer-term ramifications for the program.
The $23,760 Social Security bonus most retirees completely overlook
If you’re like most Americans, you’re a few years (or more) behind on your retirement savings. But a handful of little-known “Social Security secrets” could help ensure a boost in your retirement income.
One easy trick could pay you as much as $23,760 more… each year! Once you learn how to maximize your Social Security benefits, we think you could retire confidently with the peace of mind we’re all after. Join Stock Advisor to learn more about these strategies.
View the “Social Security secrets” »
The Motley Fool has a disclosure policy.